How Fast Is Digital Banking Adoption Really Moving Across the GCC?
72% of UAE banking customers are mobile-first and Saudi Arabia beat its own cashless targets a year early. What GCC digital banking adoption numbers mean for the next wave of products.

Ask someone in the Gulf when they last walked into a bank branch for something other than a passport-sized photo requirement, and the answer is often measured in years. The shift to mobile-first banking in the region did not happen gradually. It happened fast, and the numbers back that up.
How Many People in the Gulf Already Bank Primarily on Mobile?
In the UAE, 72% of banking customers now use a mobile app as their primary banking channel, compared with 46% in Saudi Arabia. In Qatar, a separate measure found that 94% of bank customers have used at least one digital banking channel, a figure driven partly by more than 75% smartphone penetration nationally.
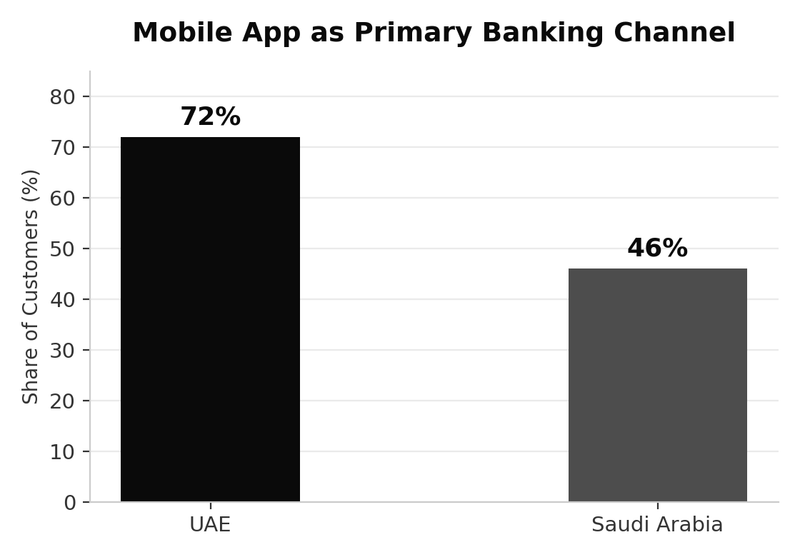
Share of banking customers who name mobile as their primary channel
Source: Arthur D. Little, Omnichannel Banking Survey 2024
Is Saudi Arabia Really Ahead of Its Own Targets?
Yes. Electronic payments reached 79% of all retail transactions in Saudi Arabia in 2024, beating the Kingdom's own cash-lite target under Vision 2030 a year ahead of schedule. The country's mobile payments market, worth $29.02 billion in 2026, is projected to reach $50.8 billion by 2031, and its real-time payment rail, Sarie, processed 10.8 billion transactions in a single year, a 24% annual jump that reset what a normal transaction speed even means for consumers.
Source: Mordor Intelligence, Saudi Arabia Mobile Payments Market
How Fast Are Neobanks Actually Growing in the Region?
Middle East neobanks served roughly 32 million customers, up 28% from 25 million in 2021, while the number of distinct digital banking offerings in the region grew 52% in under two years. That still implies penetration below 10% of the addressable population, well under the International Monetary Fund's 17% estimate for comparable emerging markets, meaning the growth curve is still in its early, steep section rather than flattening out.
Source: Fintech News UAE, citing C-Innovation
Why Do Banks Claim Digital Transformation but Fall Short?
80% of banks in the UAE and Saudi Arabia say they prioritize digital transformation, but a much smaller share actually deliver the seamless, always-on experience their customers expect.
Source: Arthur D. Little, Omnichannel Banking Survey 2024
That gap between stated priority and delivered experience is the real opportunity. It is one thing for a legacy institution to announce a digital roadmap. It is another to build the product natively for mobile from the first line of code, without a branch network's habits and assumptions baked into the experience.
What Does This Mean for a New Digital-First Bank?
The region has already answered the adoption question. Customers are ready, comfortable, and in many cases already primarily mobile. What remains open is which products actually meet the standard customers say they want but rarely get from institutions retrofitting an app onto decades-old infrastructure.
That is the gap Able is building into, in a market where the audience has already made the shift and is simply waiting for a product built for where they already are.
//
early Access — UAE first
Be first. Be Able.
Join the waitlist now. UAE, Saudi Arabia, and Qatar launch first. Early users get priority onboarding, locked-in yield rates, and zero fees for the first year.